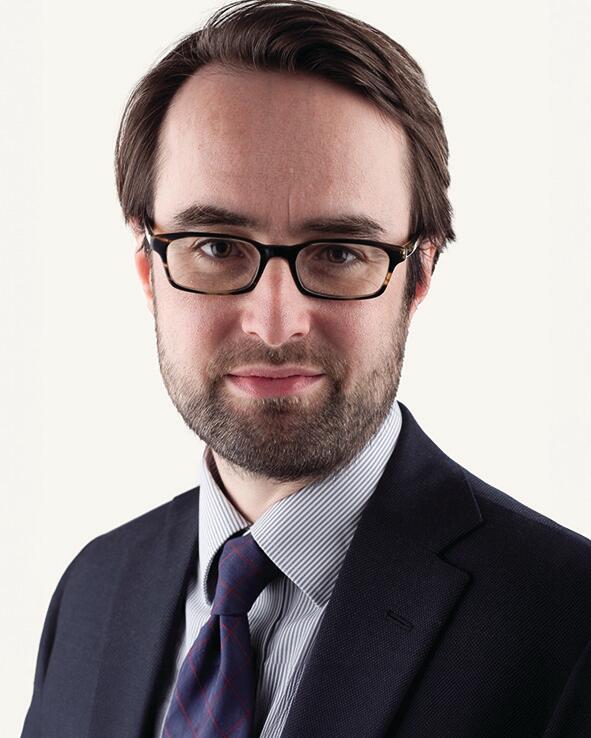
Charles Yorke (Allen & Overy) examines a recent decision which debunks a number of assumptions about the approach of both HMRC and tribunals towards accounting evidence.
If you or your firm subscribes to Taxjournal.com, please click the login box below:
If you do not subscribe but are a registered user, please enter your details in the following boxes:
Charles Yorke (Allen & Overy) examines a recent decision which debunks a number of assumptions about the approach of both HMRC and tribunals towards accounting evidence.
If you or your firm subscribes to Taxjournal.com, please click the login box below:
If you do not subscribe but are a registered user, please enter your details in the following boxes: