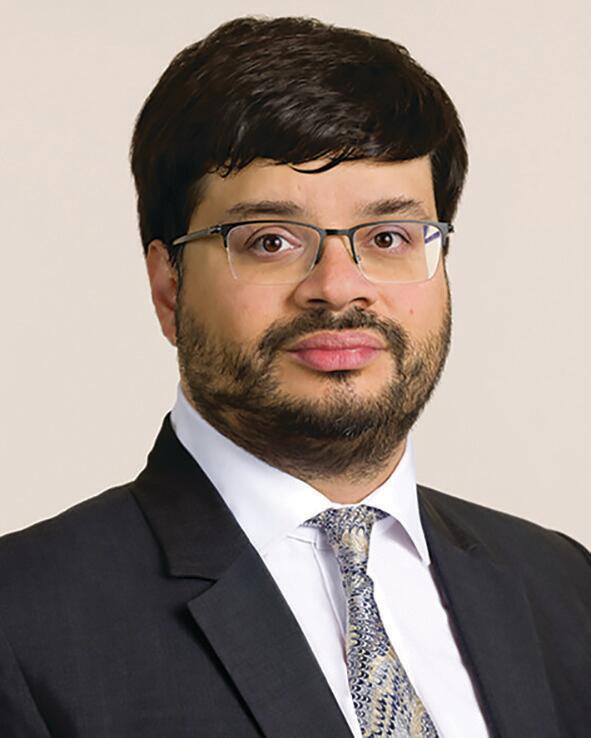
The First-tier Tribunal’s ruling in Osmond and Allen reveals a mistaken approach to the transactions in securities rules, and to purpose tests in general, writes Thomas Chacko (Pump Court Tax Chambers).
If you or your firm subscribes to Taxjournal.com, please click the login box below:
If you do not subscribe but are a registered user, please enter your details in the following boxes:
The First-tier Tribunal’s ruling in Osmond and Allen reveals a mistaken approach to the transactions in securities rules, and to purpose tests in general, writes Thomas Chacko (Pump Court Tax Chambers).
If you or your firm subscribes to Taxjournal.com, please click the login box below:
If you do not subscribe but are a registered user, please enter your details in the following boxes: